CPOS: Tap to Pay Card Reader

- 155.00 Reviews
- 4.4
- Downloads
- 10.00K
- 2.34.0
- Version
Screenshots
Download
Get It On Download on the Play Store Download on the Download on the Apple Store Get the APK APK DownloadPros
- Turns compatible phones into a convenient contactless payment terminal.
- Reduces the need for dedicated card-reading hardware.
- Supports quick tap-based transactions for eligible cards and wallets.
- Useful for mobile sellers
- freelancers
- and small businesses.
- Can make checkout easier in pop-up or on-the-go sales settings.
Cons
- Requires a compatible NFC-enabled device and supported operating system.
- Availability and features may vary by country or payment provider.
- Transaction fees can affect the value for low-margin businesses.
- A stable internet connection may be needed to process payments.
- Phone battery or hardware issues can interrupt checkout unexpectedly.
Review of CPOS: Tap to Pay Card Reader Appxis
Turning a phone into a payment terminal sounds simple until you try to use one in the middle of a busy day. A customer wants to pay, you are standing somewhere unfamiliar, and the difference between a smooth checkout and an awkward delay often comes down to the phone’s connection. That is the part of CPOS: Tap to Pay Card Reader I paid closest attention to. It is a business app from CPOS that aims to make card acceptance possible through a phone, without asking a small seller to carry a separate reader.
My overall impression is that it is most interesting for people who need mobility more than a full retail system. A market stall, independent service provider, delivery worker, tutor, repair specialist, or occasional seller can see the appeal immediately. The app is free, rated for Everyone, and has reached over ten thousand installs, with a 4.4 average from more than two hundred ratings. Those figures suggest a useful level of interest, but they do not remove the practical question that matters most: will it behave predictably when the phone is moving between networks?
How CPOS feels when the connection matters
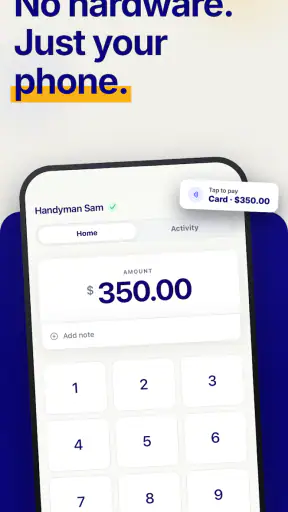
The central experience is not just tapping a card against a phone. It is preparing the phone, opening the payment workflow, entering the amount carefully, and waiting for the transaction to move through the necessary steps. In a place with a strong mobile connection, that process can feel pleasantly direct. The phone is already in your hand, so there is less equipment to remember and less space needed on a counter.
Connectivity becomes noticeable whenever the signal changes. A payment can feel immediate in one location and hesitant a few minutes later, even when nothing about the customer’s card has changed. That makes the app better suited to a seller who treats the phone as part of the payment setup, rather than as a magic replacement for every part of a traditional terminal. I would test it at the exact places where I plan to work instead of assuming that a good connection at home guarantees the same result outdoors.
One practical habit helped me think about the app more realistically: I would prepare the phone before the customer is ready to pay. That means keeping the device charged, closing distracting apps, checking the connection, and knowing where the payment screen begins. These are small steps, but they reduce the amount of time a customer spends watching a loading screen. With a phone-based reader, general phone readiness becomes part of checkout discipline.
The app’s store summary emphasizes starting without hardware or monthly fees, and that explains its strongest appeal. A separate reader can be easy to misplace, forget, or leave uncharged. CPOS puts the payment tool in the device many people already carry. For a business that takes payments only now and then, that lower equipment burden can matter more than having a large collection of advanced sales tools.
Where a mobile card reader makes sense
I can see this working well for a photographer collecting a final balance after a session, a cleaner accepting payment at a client’s home, or a craft seller who does not want to build a permanent checkout stand. In those situations, the phone is already being used to communicate with the customer, confirm the service, or record the order. Adding payment to the same device keeps the workflow compact.
There is also a useful distinction between occasional mobility and constant mobility. Someone who moves between several indoor rooms with reliable Wi-Fi may find the experience straightforward. Someone who works in basements, rural areas, crowded venues, or places with unpredictable cellular coverage needs more caution. The app can reduce hardware, but it cannot make a weak connection behave like a strong one.
I would not choose it automatically for a busy shop with several employees and a long queue. In that environment, a dedicated terminal or a broader point-of-sale system may be easier to manage because it is designed around repeated transactions, staff handoffs, and a fixed checkout position. CPOS is more compelling when the phone itself is the natural center of the business.
What changes when you leave the counter
Using a payment app away from a desk changes the little details. Sunlight can make the display harder to read. One-handed use can make amount entry more error-prone. A protective case may affect how comfortably a customer can tap a card against the phone. None of these issues is unique to CPOS, but they become more important when the whole reader is the handset.
I would create a repeatable position for the phone during payment. Holding it flat on a small table, keeping the screen visible to the customer, and avoiding unnecessary movement makes the interaction easier to understand. If the customer cannot tell where to tap or whether the phone is ready, even a technically successful transaction can feel uncertain.
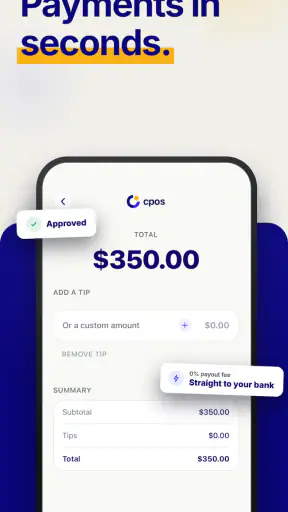
Another useful workflow is to separate payment preparation from payment confirmation. Before inviting the customer to tap, I would verify the amount and make sure the right transaction screen is visible. Afterward, I would wait for the app to finish its response instead of immediately switching to another task. This is especially important when the network is busy, because repeatedly starting the process can create confusion about whether one or more attempts went through.
The app is available for Android devices running version 8.0 or later, which gives it a broad potential device range. Still, operating-system compatibility is not the same as an equally good experience on every phone. Screen size, battery condition, network hardware, and the phone’s general performance can all affect a mobile checkout. I would use a device that is dependable rather than automatically assigning an old spare phone to payment duties.
When a transaction hesitates or fails
The most important limitation is the uncertainty created by a delayed response. If the connection drops at the wrong moment, the seller may not know whether to retry, wait, or check the transaction history. That is not merely a technical annoyance: a duplicate attempt can create a customer-service problem, while refusing to retry can leave a legitimate sale unfinished.
My advice is to build a calm recovery routine before the first real customer arrives. If the screen appears stuck, avoid tapping repeatedly. Give the process a moment, check whether the phone has regained a connection, and look for a clear transaction result before attempting anything again. If the customer’s bank shows a pending charge but the seller has no clear confirmation, pause and resolve that uncertainty rather than immediately submitting a second payment.
This is where a second communication method can be valuable. A seller might need to contact the customer, record the order details, or move to another payment option. I would keep a simple written note of the amount and customer name when appropriate, not as a replacement for a confirmed transaction but as a way to reconstruct what happened if the connection fails. The exact record-keeping method depends on the business, yet the principle is universal: do not rely on memory during a busy interruption.
Before using CPOS at an event, I would run several small test transactions in the same physical area and at a similar time of day. A test at a quiet home network tells me very little about a crowded venue. Testing the full routine also reveals practical friction, such as entering amounts, showing the phone to a customer, and locating the result after the payment attempt.
Recovery is easier when the seller knows what “finished” looks like. I would not treat a customer’s successful tap or a brief vibration as the final word. The app’s own completed state should guide the decision to move on. If that confirmation is not visible, the transaction deserves attention before the next customer steps forward.
Using it without wasting mobile data
A payment workflow should not consume attention, battery, or connectivity carelessly. I would avoid running unnecessary downloads or video calls on the same phone while taking payments, particularly when using mobile data. Keeping the device focused on the transaction reduces competition for the connection and makes the phone less likely to become warm or sluggish.
It is also sensible to distinguish between the app’s payment activity and unrelated phone activity. Automatic updates, cloud backups, and social feeds may be useful, but they do not need to compete with a checkout moment. A seller who uses a personal phone for work should review general device habits and reserve enough battery and data for the period when customers are most likely to pay.
Battery planning deserves more attention than it usually gets. A phone that starts the day at a low charge may be fine for messages but unreliable as a payment device after hours of screen use and mobile connectivity. I would carry a power bank or arrange access to charging when working away from a fixed outlet. This is not an extra feature of CPOS; it is a consequence of making the phone the payment tool.
Privacy also benefits from a deliberate routine. I would keep the customer-facing screen limited to what is necessary, avoid exposing unrelated notifications, and use a device lock outside the payment moment. A shared business phone should have a clear owner and a simple handoff process. These precautions make the phone feel more like a controlled work device and less like a personal screen casually passed around.
For sellers with limited data plans, I would monitor normal usage during the first few working sessions rather than guessing. The important point is not to invent a fixed data expectation, because usage depends on the phone, network, and broader device activity. Instead, watch the plan, keep nonessential traffic under control, and make connectivity part of the operating checklist.
How it compares with the usual alternatives
The obvious alternative is a dedicated card reader. A separate terminal generally gives the payment function its own physical home, which can be reassuring for a fixed counter or a team. It may also be easier for staff to recognize and share. The trade-off is carrying, charging, pairing, and maintaining another piece of hardware.
CPOS has the opposite character. Its advantage is compactness: the seller can work with a phone instead of adding a reader to the bag. That is valuable for appointments, deliveries, temporary tables, and businesses that do not take card payments every hour. The compromise is that phone condition and network quality become central to the checkout experience.
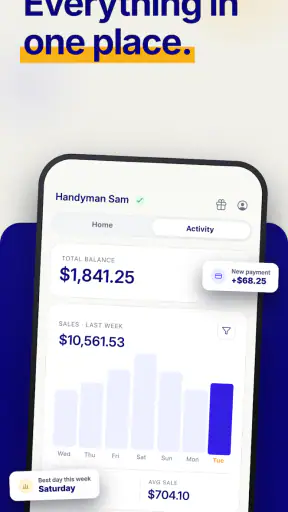
A larger point-of-sale application can be a better match for a store that needs inventory, employee permissions, detailed reporting, or a complete product catalog. CPOS should not be judged unfairly for not being a full retail back office when its main appeal is turning a phone into a card reader. At the same time, a seller should not expect a compact payment tool to replace every administrative system used by a growing business.
Cash remains useful in locations where connectivity is unpredictable, while bank transfers or payment links may suit customers who are comfortable completing a transaction on their own device. Those options introduce their own delays and verification steps. I would treat CPOS as one part of a sensible payment plan, especially for mobile work, rather than as a reason to discard every backup method.
Who should install it, and who should wait
I would recommend trying CPOS if you are an independent seller who wants to accept card payments without committing to extra equipment. It is particularly attractive when your work moves between customers and when your phone is already central to scheduling, communication, and receipts. The free price makes experimentation easier, and the Everyone age rating keeps the app broadly approachable from a content perspective.
I would be more cautious if your business depends on uninterrupted, high-volume checkout. A restaurant queue, a busy shop, or a team of employees may benefit from a dedicated terminal and a system designed for shared operations. I would also hesitate if your usual work locations have unreliable mobile service and no dependable network alternative. The app can simplify hardware, but it cannot remove the operational consequences of poor connectivity.
The current version is 2.34.0, and the app was released on January 17, 2025. I mention that because a relatively recent business tool deserves a short trial period in the real environment where it will be used. Install it on the intended phone, test the complete customer interaction, and decide based on repeated behavior rather than on the idea of a phone reader alone.
One detail I would settle before relying on it is the business’s own payment procedure: who checks the amount, who confirms completion, and where the transaction is recorded afterward. A solo worker can keep this simple. A team needs a shared rule, otherwise a connection delay can become a communication failure between employees. The app may start the payment, but the surrounding workflow determines whether the business stays organized.
My connectivity verdict
After looking at CPOS through the realities of mobile connectivity, I see a focused tool with a clear audience. It makes sense for people who value carrying less and already have a suitable Android phone. The strongest experience comes when the seller plans for signal quality, battery life, customer positioning, and a clear response to delayed transactions.
What I like most is the reduction in equipment. For a small service business, avoiding a separate reader can make occasional card acceptance feel much less complicated. What I would not ignore is the dependence on the phone’s working condition and network context. A smooth tap is only one part of the experience; preparation and recovery matter just as much.
My recommendation is to treat CPOS as a practical mobile payment option, not as a universal replacement for a full checkout system. If your work is flexible, your connection is dependable, and your payment volume is moderate, it is worth trying. If your business needs a permanent, highly managed counter or cannot tolerate uncertainty during a network interruption, a dedicated alternative will probably serve you better.
In short, CPOS: Tap to Pay Card Reader earns its place by making the phone useful in a situation that normally calls for another device. I would install it for a mobile side business or independent service workflow, test it at real customer locations, and keep a backup plan for weak-signal moments. That approach matches what the app does best: simplify card acceptance while leaving the seller responsible for the conditions that make a phone-based checkout dependable.
FAQ
What is CPOS: Tap to Pay Card Reader?
CPOS: Tap to Pay Card Reader is a mobile point-of-sale solution designed to help businesses accept card and contactless payments using a compatible smartphone or tablet. Instead of relying only on a traditional payment terminal, the app can turn supported devices into a convenient payment tool. Availability, supported payment methods, and account features may depend on the provider, country, and device model.
How does Tap to Pay work with CPOS?
After setting up a merchant account and completing any required verification, the user can enter a transaction amount in CPOS and ask the customer to tap a contactless card, phone, or smartwatch against the device. The payment is then processed through the app and the customer receives confirmation. A compatible NFC-enabled device, internet connection, and supported payment service are generally required.
Is CPOS: Tap to Pay Card Reader safe for accepting payments?
CPOS is intended for business payment processing and uses the security mechanisms provided by the payment platform and the device’s operating system. Contactless transactions typically use encrypted communication and tokenized payment information rather than exposing the customer’s complete card details. However, merchants should keep the app updated, protect account credentials, use screen security, and review the provider’s terms before processing real transactions.
What devices and payment methods are supported by CPOS?
Support can vary according to the CPOS version, operating system, location, and payment processor connected to the account. In general, users should check whether their Android or iOS device includes compatible NFC hardware and meets the app’s minimum requirements. The service may support contactless bank cards and mobile wallets, while magnetic-stripe or chip-and-PIN transactions could require additional hardware.
Are there fees or an internet connection required to use CPOS?
Using CPOS may involve transaction fees, subscription costs, account charges, or other pricing conditions established by the payment provider. These costs can differ by country, business type, and selected plan, so they should be confirmed before downloading or activating the service. An internet connection is normally needed to authorize and record payments, although offline functionality, if available, may be limited.


