

Afterpay: Pay over time
AfterpayShopping
Scanned and Safe · Free
- Rating
- 4.0Out of 5
- Downloads
- 10.00M
- Android
- 7.0
Screenshots
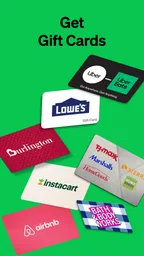
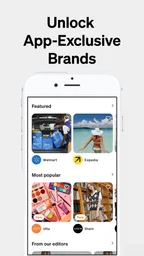
Analysis by Appxis
When I first try a pay-later app, the appeal is obvious: I can complete a purchase without paying the full amount at checkout. The more important test comes later, when the novelty wears off and the scheduled payments become part of ordinary budgeting. Afterpay is most useful when I treat it as a payment schedule for something I already planned to buy, not as extra money or a reason to add more to my basket.
The first-week appeal: a smaller checkout total
Afterpay is a free shopping app from Afterpay, and its basic appeal is easy to understand: eligible purchases can be divided into installments rather than charged all at once. I can see why that feels helpful when a necessary purchase lands at an awkward point in the month. The convenience is real, but the smaller first payment can also make a purchase feel cheaper than it is. I try to judge the full cost first, then decide whether the schedule genuinely fits.
A realistic example is replacing a worn pair of everyday shoes just before payday. If a retailer offers Afterpay at checkout, splitting the cost may be easier to manage than paying the entire amount immediately. But I would still compare the total with my budget and check the payment dates against rent, bills, and other commitments. If the purchase only seems affordable because I am focusing on the first installment, I would wait or choose a less expensive option.
Where it fits among shopping payment choices
Compared with paying by debit card, Afterpay spreads the outlay across scheduled payments, so less money leaves my account at once. Compared with a credit card, it can make the repayment plan more visible and tied to a particular purchase. Those differences can be useful, but neither changes the basic rule: the full amount still has to come from future income. If I can comfortably pay now, a regular card or debit payment is simpler and gives me fewer dates to keep track of.
I also see a distinction between using it for one planned purchase and relying on it for several unrelated carts. One schedule may be easy to remember; several overlapping schedules can quietly crowd the same pay period. Before choosing the option, I would look at the upcoming commitments together rather than assess each checkout on its own. That small pause is more valuable than treating installment payments as separate from my normal spending plan.
The app is aimed at shopping, and the product is made by Afterpay. It has an average rating of 4.0 from around 167,000 ratings, with about 70,000 written reviews and over 10 million installs. Those figures suggest it is familiar to many shoppers, but popularity alone does not tell me whether it suits my habits. The app is free, rated for Everyone, and version 1.128.0 supports Android 7.0 and later.
Shop Till You Drop
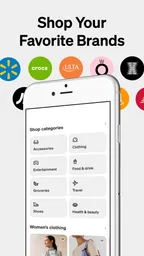
The first thing you'll notice with Afterpay is just how easy it is to use. After downloading the app, you can quickly set up your account and start shopping at your favorite stores. Whether you're picking up the latest fashion trends, tech gadgets, or even beauty products, Afterpay has partnered with a wide range of retailers. What I love most is that there's no interest or additional fees if you pay on time, which feels like a win-win situation for us shopaholics.
More Stories While You Read






How It Works
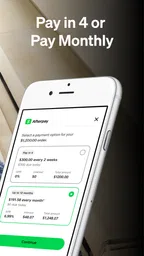
Using Afterpay is pretty straightforward. When you're ready to make a purchase, choose Afterpay at checkout. Your total amount is then split into four equal installments, payable every two weeks. The best part? The first payment is due at the time of purchase, and the subsequent payments are automatically deducted from your chosen payment method. It's like having a mini layaway plan without the wait.
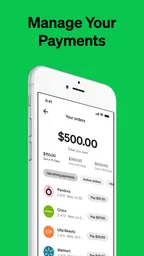
What's also cool about the app is its user-friendly interface. The dashboard is clean and intuitive, letting you track your spending, view upcoming payments, and even browse new stores to shop at. Plus, the app sends reminders before each payment is due, so you won't be caught off guard. Trust me, this feature is a lifesaver if you're juggling multiple expenses.
Is It For You?
Now, you might be wondering if Afterpay is the right fit for you. If you enjoy shopping online and prefer spreading out your payments without incurring interest, then this app is definitely worth considering. However, it's essential to budget wisely and ensure you can meet those payment deadlines to avoid any late fees. As someone who's occasionally been guilty of impulse buying, I can attest that Afterpay can help manage those urges while still allowing a bit of retail therapy.
It's also worth noting that Afterpay is geared towards those with good financial discipline. If you're someone who struggles with debt management or tends to overspend, this app might not be the best choice. Financial responsibility is key to making the most out of what Afterpay offers.
The month-to-month value is about habits
After the first few purchases, I would judge the app less by how quick checkout feels and more by whether it helps me stay organized. The useful habit is to check the payment schedule before placing another order, then leave enough room in the monthly budget for every upcoming installment. A reminder can prompt me to prepare, but it cannot decide whether a new purchase is sensible. I still need to review the total amount I have committed to spending.
One practical approach is to keep a simple note of purchases made through the app and their remaining installments, especially if I am also using a card or another payment service. That gives me one view of future obligations instead of relying on memory or checking each order only when a reminder arrives. It is a small bit of maintenance, but it helps reveal when several individually manageable purchases are adding up to a tight week.
The app makes more sense to me for occasional, planned shopping than for routine spending that happens every few days. A seasonal clothing purchase or a needed household item has a clear purpose and a finite schedule. Using installments for small treats repeatedly can make the payment dates feel normal while making the underlying shopping habit more expensive in attention and harder to track. If I notice I am opening the app mainly to find another reason to buy, I would take that as a cue to pause.
Maintenance without turning shopping into a chore
There is no complicated routine needed to get value from Afterpay, but a little attention matters. I would check the amount and dates before confirming a purchase, make sure the chosen payment method is current, and keep enough funds available for scheduled deductions. I would also read the checkout terms for the specific order rather than assume every purchase follows the same arrangement. Those checks are especially helpful when I have several expenses due close together.
For someone who shares household costs, the app is easiest to manage when the person making the purchase is also the person tracking its repayments. If a partner or family member is expected to contribute, I would agree on that before checkout rather than count on a transfer later. The schedule belongs in the budget even if another person intends to help. That avoids turning a convenient purchase into an awkward conversation when a payment date arrives.
It is also worth separating a return or exchange decision from the payment schedule in your mind. If an item does not work out, I would follow the retailer’s return process and then check how the purchase is reflected in the app, rather than assume the installments simply disappear as soon as I send something back. Keeping receipts and order details together makes that follow-through easier. This is not a reason to avoid the service; it is a reminder that installment payments do not remove the ordinary work of managing an online order.
When the convenience starts to feel tiring
The main source of fatigue is not the interface; it is having too many dates and commitments to remember. A few automatic deductions can be easy to overlook when they fall between paydays or coincide with bills. Notifications help, but I would not treat them as a substitute for checking my account balance and the schedule. If monitoring the installments starts to take more effort than paying upfront, the simpler option may be better.
Another trade-off is how the checkout choice can affect judgment. Splitting a purchase may reduce the immediate hit to cash flow, but it can also encourage me to choose a more expensive version or buy sooner than I otherwise would. I would compare the item against a lower-cost alternative and ask whether I would still want it if the full total were due today. If the answer changes only because of the payment plan, I would reconsider.
Afterpay is not the right tool for someone who is already struggling to cover essentials, routinely carries unpaid balances, or cannot reliably keep track of scheduled deductions. In that situation, delaying a purchase, saving first, or choosing a cheaper item is safer than adding another commitment. It may also be a poor fit for shoppers who want one payment method for every retailer: availability depends on the checkout, so I would not build a shopping plan around assuming the option will appear everywhere.
Who is likely to keep it installed?
I can see lasting value for a shopper who uses it selectively, likes having a purchase schedule visible, and has enough financial breathing room to cover each installment. The app can be convenient when a planned order is available through it and the dates fit the budget. Someone who prefers to pay in full, avoids installment products, or finds multiple due dates stressful may get more peace of mind from a debit card or from waiting until the money is already set aside.
For a first-time user, I would begin with one purchase I already intended to make, rather than test the app by browsing for extra items. Before confirming, I would check the full total, note the repayment dates, and make sure the first payment does not leave too little for immediate essentials. Afterward, I would see whether the reminders and payment tracking genuinely made the purchase easier to manage. That first experience is a better guide than the appeal of a quick checkout.
Let's chat about Afterpay - a finance app that's making waves in the world of online shopping. If you're like me and occasionally cringe when checking out due to the total amount, Afterpay might just be your new best friend. It's a nifty app that lets you buy now and pay later, spreading out the cost of your purchases over several weeks. So, let's dive in and see what this app is all about.
Is It For You?
Now, you might be wondering if Afterpay is the right fit for you. If you enjoy shopping online and prefer spreading out your payments without incurring interest, then this app is definitely worth considering. However, it's essential to budget wisely and ensure you can meet those payment deadlines to avoid any late fees. As someone who's occasionally been guilty of impulse buying, I can attest that Afterpay can help manage those urges while still allowing a bit of retail therapy.
It's also worth noting that Afterpay is geared towards those with good financial discipline. If you're someone who struggles with debt management or tends to overspend, this app might not be the best choice. Financial responsibility is key to making the most out of what Afterpay offers.
My long-term verdict
For me, the test of whether Afterpay deserves a permanent place on a phone is whether I use its payment schedule without letting it shape what I buy. Its day-to-day value comes from keeping a planned purchase manageable and making upcoming payments easier to see. If it becomes a prompt to shop more often, the convenience has stopped serving me. I would keep it as an occasional option, not as a default way to check out.
In conclusion, Afterpay stands out as a flexible and convenient option for online shoppers looking to manage their finances smartly. With its no-interest payment plans and wide range of partner stores, it's no surprise that it's gaining popularity. Just remember to shop responsibly, and you'll likely find Afterpay to be a valuable addition to your shopping toolkit. Happy shopping!
Pros
- Easy to use interface
- Interest-free payments
- Wide range of participating stores
- No credit check required
- Flexible payment schedule
Cons
- Late fees apply
- Not available everywhere
- May encourage overspending
- Requires linking a card
- Limited customer support
Afterpay: Pay over time FAQ
What is Afterpay and how does it work?
Afterpay is a financial technology service that allows users to purchase items immediately and pay for them over time in four equal installments. Once you select Afterpay at checkout, the first payment is made at the time of purchase, and the remaining three payments are automatically deducted every two weeks. This enables budget-friendly shopping without the need for credit checks or interest fees.
Is Afterpay available for both Android and iOS devices?
Yes, Afterpay is available for download and use on both Android and iOS devices. The app can be found on the Google Play Store for Android users and the Apple App Store for iOS users. The interface is user-friendly on both platforms, ensuring a seamless experience regardless of the device you are using.
Are there any fees or interest associated with using Afterpay?
Afterpay does not charge any interest or upfront fees for using its service, making it an attractive option for budget-conscious shoppers. However, if you miss a scheduled payment, a late fee may be applied. It's important to ensure sufficient funds in your account to avoid these additional charges and maintain a positive payment history.
What types of retailers accept Afterpay as a payment option?
Afterpay is accepted by a wide range of retailers, from fashion and beauty to electronics and home goods. Many popular online and physical stores have integrated Afterpay into their payment options, providing flexibility and convenience for shoppers. You can easily check the list of participating retailers in the Afterpay app or on their website.
How does Afterpay impact my credit score?
Afterpay does not conduct credit checks when you apply for an account, and using Afterpay will not directly affect your credit score. However, consistently missing payments and accruing late fees may impact your creditworthiness in the future. It's essential to manage your Afterpay account responsibly to avoid potential negative effects on your financial profile.
Read This Page in Another Language
Other Picks in This Category

SHEIN-Shopping Online
Roadget Business PTE. LTD. 4.8 Out of 5

Temu: Shop Like a Billionaire
Temu 4.4 Out of 5

Amazon Shopping
Amazon Mobile LLC 4.4 Out of 5

Mercado Libre: Compras online
Mercado Libre 4.8 Out of 5
More Shopping Reviews

Wish: Shop and Save
Wish US Holdings LLC 4.7 Out of 5

Alibaba.com - B2B marketplace
Alibaba Mobile 4.4 Out of 5

AliExpress - Shopping App
Alibaba Mobile 4.3 Out of 5

Wildberries
Wildberries LLC 4.5 Out of 5

Groupon – Deals & Coupons
Groupon, Inc. 4.4 Out of 5

OLX: Compras Online e Vendas
OLX Brasil 4.4 Out of 5
About This Listing
- Developer
- Afterpay
- Package Name
- com.afterpaymobile.us
- Version
- 1.142.0
- Android
- 7.0
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at info@afterpay.com.au, visit https://www.afterpay.com, or view the https://www.afterpay.com/en-US/privacy-policy.