

Affirm: Buy now, pay over time
Affirm, IncShopping
Scanned and Safe · Free
- Rating
- 4.8Out of 5
- Downloads
- 10.00M
- Android
- 10
Screenshots
Analysis by Appxis
In a shared household, an online purchase can become a small group decision: one person spots a needed replacement, another checks what is already budgeted, and everyone wants to know what the commitment will look like before pressing the final button. That is the practical setting where I find Affirm easiest to assess. It is a shopping app from Affirm, Inc that offers a way to spread eligible purchases across payments, but it should be treated as a payment commitment rather than a household budgeting tool or a reason to buy more.
When a purchase affects more than one person
Picture a shared home where a necessary appliance or work item has to be replaced. Instead of relying on memory or a vague estimate, the person shopping can review the payment choices shown at checkout and bring the actual schedule back to the household conversation. That makes it easier to ask a useful question: does this fit alongside the bills and expenses already planned for the coming weeks?
I would keep the decision tied to the specific item and its displayed terms. A payment plan can make the immediate checkout feel lighter, but it does not make the purchase cheaper by itself. Before agreeing, I would compare the total cost with paying another way and make sure the people sharing the budget understand who is responsible for each payment.
Keep account access and responsibility clear
For a household using a shared phone or tablet, I would avoid treating one signed-in financial account as a communal shopping profile. Each person should understand whose account is open, who is making the purchase, and whose payment method or repayment obligation is involved. Passing a device around without checking the account first can turn a quick checkout into a confusing one.
A sensible routine is to let one adult handle the transaction, then share the relevant purchase and payment details with anyone who needs to plan around it. Do not assume that a shared device means shared access is appropriate, or that another household member can manage an account on the account holder’s behalf. The app is most useful when the person accepting the terms can keep track of the commitment themselves.
Coordinate before checkout, not after
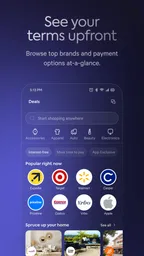
Affirm can help make a proposed purchase easier to discuss because the payment options appear before the user commits. I would use that moment to pause, check whether the item is genuinely needed now, and compare the proposed payments with the household’s existing plans. If another person will contribute, agree on the amount and timing beforehand rather than relying on an informal promise after the purchase is complete.
This approach also helps with returns or changes of mind: the buyer should keep the order and payment information together and make sure everyone knows who will follow up. A pay-over-time arrangement adds a second timeline to an ordinary shopping decision, so clear responsibility matters as much as choosing a comfortable amount.
More Stories While You Read






Ever found yourself eyeing something online but not quite ready to commit to the full price tag? Enter Affirm, the app that allows you to buy now and pay over time. If you’re anything like me, you’ll appreciate the flexibility this app brings to the table. Let’s dive into how it works and what makes it a must-have in your financial toolkit.
What is Affirm?
Affirm is a financial service app that lets you split purchases into smaller, manageable payments. Think of it as your personal financial buddy that helps you spread the cost of that new gadget or wardrobe update over several months. Its seamless integration with various online retailers makes shopping a breeze.
How Does It Work?
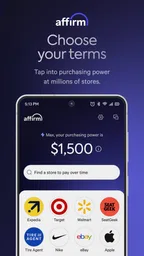
Using Affirm is straightforward. Once you’ve got your eye on something, select Affirm at checkout. You’ll see a breakdown of payment plans, which is really handy for making informed decisions. Personally, I love seeing exactly what I’m getting into before I commit. Plus, there’s no hidden fees or penalties if you pay off early, which is a huge win in my book.
Why You’ll Love It
First off, let’s talk about the user interface. It’s clean, intuitive, and super easy to navigate. Honestly, I’ve used a fair share of financial apps, and this one’s design is top-notch. Then there’s the approval process, which is quick and doesn’t leave you hanging. One minute you’re applying, and the next, you’re all set to shop!
Is It Safe?
Security can be a concern with financial apps, but Affirm has you covered. With robust encryption and privacy controls, you can rest assured your personal information is safe. I’ve never had an issue with security while using the app, and that peace of mind is priceless.
Flexibility at Its Best
One thing that stands out for me is the flexibility Affirm offers. Whether you’re buying something small or splurging on a big-ticket item, being able to choose a payment plan that fits your budget is incredibly empowering. It’s like having the power to tailor your financial obligations to your lifestyle.
How I’d weigh it against other ways to pay
Affirm belongs in the shopping-app conversation, but I would not compare it only with other checkout buttons. The real alternatives are paying in full from available funds, waiting until the purchase fits the budget, or using a credit card whose terms the buyer already understands. Paying in full is simpler and avoids adding another schedule to track. Waiting is often the better choice for a nonessential upgrade. Affirm’s appeal is strongest when the item is needed, the displayed terms are clear, and dividing the expense helps someone plan without losing sight of the total.
That comparison is worth making each time rather than choosing a payment method out of habit. I would check the full amount, the due dates, and whether the proposed installments sit comfortably beside rent, utilities, groceries, and other obligations. If the plan only works by assuming everything else goes perfectly, I would postpone the purchase or choose a less costly option. Convenience at checkout is not the same as affordability.
A practical way to use the checkout screen
One useful habit is to decide on a personal spending limit before browsing, then treat the payment choices as a way to evaluate a purchase—not as permission to stretch that limit. When the options appear, I would compare the schedule with the item’s value and expected useful life. Spreading the cost of something durable that is genuinely needed may make more sense than using installments for several small, forgettable purchases that accumulate into a larger obligation.
I would also avoid making several separate decisions in quick succession. Before confirming another purchase, look at what is already due and consider whether the new plan would overlap with existing commitments. This simple pause is especially helpful in a household where multiple people shop for shared needs: a shared note or conversation can clarify what has already been ordered, without handing around account credentials or assuming everyone can see the same account details.
Who is likely to get the most from it?
I can see Affirm suiting an adult who shops online, wants to understand the payment schedule before committing, and is comfortable keeping track of more than one due date. It may be particularly useful when a planned, necessary purchase cannot sensibly wait until the next budgeting cycle and the available terms fit the buyer’s finances. The app is free, has an Everyone content rating, and its broad adoption—over ten million installs and an average rating of 4.8 from around 532,000 ratings—suggests many shoppers find the service useful, though popularity cannot tell you whether an individual plan is right for you.
I would skip it for impulse buys, for purchases that are already difficult to afford, or if managing scheduled payments tends to be stressful. It is also not the best fit for someone who prefers a single payment and does not want another account or payment timeline to monitor. A lower-cost product, waiting, or paying in full may be a better choice even when a split-payment option is available.
Age, trust, and household expectations
The Everyone rating describes the app’s content classification; it should not be read as a signal that every user is ready to take on a financial commitment. In a household with younger people, I would keep purchasing decisions and account responsibility with an adult who understands the terms. No family-management setup should be assumed: a shared device does not replace a direct conversation about permission, spending limits, or who is accountable.
Trust also means being honest about uncertainty in a household budget. If one person is unsure they can cover a future installment, the group should not treat the plan as settled simply because checkout was approved. I would rather delay a purchase than ask someone else to absorb an obligation they did not agree to.
What to check before deciding
Before accepting an offer, read the payment details shown for that purchase and make sure the schedule is understandable. Consider the total you will pay, the dates, the consequences of missing a payment, and whether your circumstances could change. Terms can depend on the specific transaction, so I would rely on what is presented for that purchase rather than assuming every checkout will work the same way.
It is also worth asking whether you can manage the plan if your phone is unavailable or another household member is handling shopping that day. Keep your own record of the commitment and know where you will check its status. That is a practical safeguard, not a substitute for reading the terms or staying current.
Version and everyday fit
The current version is 3.402.1, and the app runs on Android 7.0 or later. Those details matter if you are considering installing it on an older phone, but the essential question remains whether it fits the way you shop. I would use it deliberately for selected purchases, not as a default button for every online order.
Affirm has been available since June 20, 2016, and its free download lowers the barrier to trying the app. That does not mean every payment plan costs nothing or that every user will receive the same options. I would distinguish the cost of installing the app from the terms attached to a particular purchase, and review those terms before deciding.
In conclusion, Affirm is a game-changer for anyone who wants to enjoy shopping without the immediate financial burden. Whether you’re a savvy shopper or someone who simply enjoys the flexibility of paying over time, this app has got your back. So next time you’re shopping online, give Affirm a go—your wallet will thank you!
My household verdict
For shared living, I see Affirm as a checkout option one responsible buyer can use after talking through a purchase—not as a shared wallet, a household ledger, or a shortcut around budgeting together. Its useful moment is the chance to inspect a payment schedule before committing. Its main trade-off is that each installment creates a future obligation that can be easy to overlook if the buyer focuses only on the smaller amount due now.
If you keep the account boundaries clear, discuss shared expenses before checkout, and choose only plans that remain manageable alongside ordinary bills, the app can be a practical tool for selected purchases. If those conditions are not in place, paying in full, waiting, or choosing something less expensive is the calmer option. That is the standard I would use before recommending it to a friend.
Pros
- Flexible payment plans available.
- User-friendly interface design.
- Quick approval process.
- No hidden fees involved.
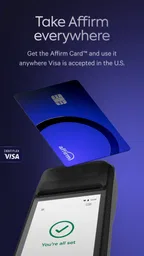
- Wide acceptance in stores.
Cons
- High interest rates on late payments.
- Limited to partnered retailers.
- Requires a credit check.
- Not available internationally.
- Potential for overspending.
Affirm: Buy now, pay over time FAQ
What is Affirm and how does it work?
Affirm is a financing option available at many retailers that allows you to purchase items immediately and pay for them over time. When you choose Affirm at checkout, you can select from several payment plans, typically ranging from three to 36 months. Affirm conducts a soft credit check to determine your eligibility, which does not affect your credit score. Once approved, you can make monthly payments directly through the Affirm app or website.
Does using Affirm affect my credit score?
Using Affirm will not impact your credit score as they perform a soft credit check during the loan approval process. However, it’s important to note that if you miss a payment or default on your loan, it could potentially affect your credit score negatively. Affirm reports to credit bureaus, so making timely payments can help improve your credit history.
What are the interest rates and fees associated with Affirm?
Affirm offers transparent financing with no hidden fees. The interest rates vary depending on your creditworthiness and the retailer, typically ranging from 0% to 30% APR. Some promotions may offer 0% financing, which means you only pay the purchase price. Affirm does not charge late fees, service fees, or prepayment penalties, making it a straightforward financing option.
Is Affirm available for all purchases?
Affirm is available at a wide range of retailers, but not every purchase qualifies for financing. The availability of Affirm as a payment option depends on the retailer's partnership with Affirm and the total purchase price. Typically, there is a minimum purchase requirement to use Affirm, and certain categories like gift cards are usually excluded from financing. Always check the retailer's checkout page to see if Affirm is offered.
How do I make payments with Affirm?
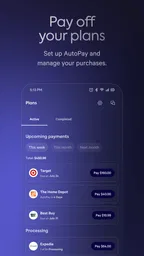
You can make payments to Affirm easily through their mobile app or website. Once your purchase is confirmed, Affirm will notify you of your payment schedule via email and through the app. Payments can be made using a bank transfer, debit card, or check. The app also allows you to set up automatic payments to ensure you never miss a due date. Affirm sends reminders to help you stay on track with your payments.
Other Picks in This Category

SHEIN-Shopping Online
Roadget Business PTE. LTD. 4.8 Out of 5

Temu: Shop Like a Billionaire
Temu 4.4 Out of 5

Amazon Shopping
Amazon Mobile LLC 4.4 Out of 5

Mercado Libre: Compras online
Mercado Libre 4.8 Out of 5
More Shopping Reviews

Wish: Shop and Save
Wish US Holdings LLC 4.7 Out of 5

Alibaba.com - B2B marketplace
Alibaba Mobile 4.4 Out of 5

AliExpress - Shopping App
Alibaba Mobile 4.3 Out of 5

Wildberries
Wildberries LLC 4.5 Out of 5

Groupon – Deals & Coupons
Groupon, Inc. 4.4 Out of 5

OLX: Compras Online e Vendas
OLX Brasil 4.4 Out of 5
About This Listing
- Developer
- Affirm, Inc
- Package Name
- com.affirm.central
- Version
- 4.89.1
- Android
- 10
- Price
- Free
This site provides independent information about third-party apps. We do not own, develop, or distribute them. Names, logos, and trademarks belong to their respective owners. Developer details are for reference only. For more information, please contact the developer at help@affirm.com, visit https://www.affirm.com, or view the https://www.affirm.com/privacy/.